First Salary, First Loan: What Gen Z Should Know Before Borrowing
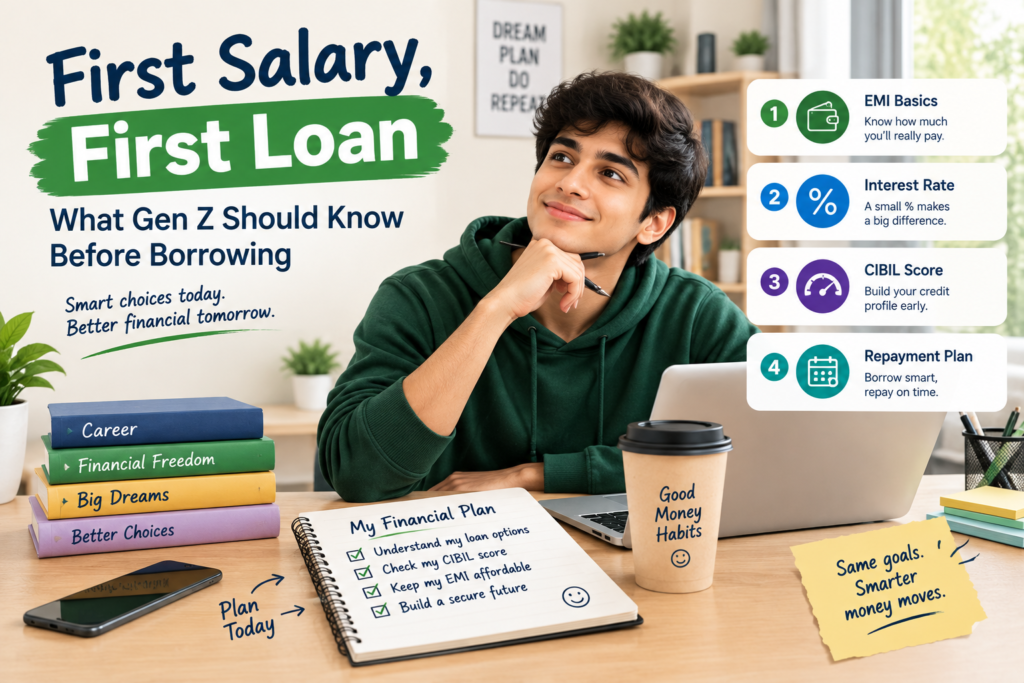
Getting your first salary feels like a big milestone. You finally have your own income, more financial independence, and the freedom to make bigger purchases. But for many young professionals, the next step can also mean considering their first personal loan, whether it is for a laptop, higher education, a family expense, relocation, a wedding, or an unexpected financial need.
Taking a personal loan is not necessarily a bad financial decision. The important part is understanding what you are signing up for before you click “Apply Now.” Your EMI, interest rate, repayment capacity and CIBIL Score can all play an important role in your borrowing journey.
1. First Ask Yourself: Do I Really Need the Loan?
Before checking your loan eligibility, first understand the reason for borrowing. A loan can be useful when you have a genuine financial requirement and a clear repayment plan. However, taking a loan simply because an app shows you an “easy EMI” can create unnecessary financial pressure.
For example, buying an expensive gadget on impulse may feel affordable when you look only at the monthly EMI. But when you add the interest and other applicable charges, the total amount you repay can be significantly higher than the original purchase price.
Before borrowing, ask yourself three simple questions: Do I really need this expense now? Can I afford the EMI every month? And what will happen if my income or expenses change?
2. Understand EMI Before You Borrow
EMI stands for Equated Monthly Instalment. It is the amount you generally pay at regular intervals toward your loan, covering both principal and interest.
For example, suppose you borrow ₹1,00,000 and the lender offers you a particular interest rate and repayment tenure. Your EMI will depend on the loan amount, interest rate and tenure.
The important point for a first-time borrower is this: don’t choose a loan only because the EMI looks small.
A longer tenure can reduce the monthly EMI, but it can also mean paying interest for a longer period. Therefore, compare both the monthly EMI and the total repayment amount before making a decision.
3. Don't Look Only at the Interest Rate
Interest rate is important, but it is not the only cost you should check.
Depending on the loan and lender, there may be processing fees, applicable taxes, late-payment charges, prepayment or foreclosure-related charges, and other terms. For digital lending products, RBI guidance requires relevant cost information such as the Annual Percentage Rate (APR) and Key Fact Statement to be disclosed to borrowers.
So instead of asking only, “What is the interest rate?”, ask:
“What is the total cost of this loan?”
Read the loan agreement and Key Fact Statement carefully before accepting the offer.
4. Your CIBIL Score Matters
Your CIBIL Score is a three-digit summary of your credit history and ranges from 300 to 900. It is based on information in your credit report, including your accounts and enquiries. CIBIL identifies payment history, credit utilisation, age of credit and enquiries among the main factors affecting the score.
For Gen Z entering the world of credit, this is important because your early borrowing and repayment behaviour can become part of your credit history.
If you take a loan, making your payments on time and managing credit responsibly can help you build a healthier credit profile. On the other hand, missed or delayed payments can negatively affect your credit profile.
Think of your CIBIL Score as a financial report card for your credit behaviour—not the only factor a lender considers, but an important one.
5. Don't Take Multiple Loans Just Because You Are Eligible
Getting a loan offer does not automatically mean you should take the loan.
One common mistake among first-time borrowers is applying for multiple loans or credit cards within a short period while looking for approval. Loan applications can result in lender enquiries being recorded on your CIBIL Report, and multiple enquiries over a short period may affect your score.
Instead, compare your options carefully, check the lender’s terms and apply only when you have identified a suitable borrowing option.
6. Keep Your EMI Affordable
Your salary is not the same as your available EMI budget.
Imagine you earn ₹30,000 per month. From that amount, you may already have expenses such as rent, food, transportation, subscriptions, family responsibilities, savings and other bills.
If you add a large EMI without considering these expenses, your monthly budget can become difficult to manage.
Before taking a loan, create a simple monthly calculation:
Monthly Income – Essential Expenses – Existing EMIs – Savings = Amount Available for New EMI
The goal should be to take a loan that you can comfortably repay rather than stretching your budget to the maximum amount a lender may offer.
7. Don't Ignore Your Credit Card
A personal loan may not be your only credit commitment. If you already use a credit card, remember that outstanding balances and credit utilisation are also relevant to your credit profile.
CIBIL advises consumers to keep credit balances low and manage utilisation prudently.
If you are already struggling to manage credit card payments, adding another EMI may increase your financial burden. Look at your complete financial picture before taking additional credit.
8. Check Your CIBIL Report Before Applying
Before applying for your first major loan, it can be useful to check your CIBIL Score and Report.
Your CIBIL Report contains information about your credit accounts, payment history and lender enquiries. CIBIL currently provides a free CIBIL Score and Report once per calendar year.
Checking your own CIBIL information is also different from a lender’s credit enquiry. CIBIL states that its report contains enquiries made by lenders for loan and credit-card applications.
If you find incorrect information, it is better to identify and address it before making an important credit application.
9. Read the Fine Print Before Saying Yes
Gen Z is used to completing transactions in a few clicks, but borrowing money should not be treated like ordering food online.
Before accepting a loan, check the loan amount, interest rate, EMI, tenure, total repayment, applicable fees, late-payment charges, prepayment terms and other important conditions.
If the offer is through a digital lending platform, also verify who the actual regulated lender is and carefully read the Key Fact Statement and other loan documents. RBI’s financial-awareness guidance specifically recommends understanding the total cost and reading loan-related documents before borrowing.
10. Your First Loan Can Set the Tone for Your Credit Journey
Your first loan is not just about getting money today. It is also about learning how responsible borrowing works.
Making timely payments, keeping credit usage under control, avoiding unnecessary applications and regularly reviewing your credit information can help you develop healthier credit habits over time. CIBIL specifically recommends timely payments, low balances and responsible management of credit.
Remember: a loan should fit your financial plan—not become the financial plan
How Manikaran Credit Can Help
At Manikaran Credit & Leasing Company, we believe that borrowing should be approached with clarity and responsibility. If you are considering a personal loan, understanding your eligibility, repayment capacity, applicable charges and loan terms can help you make a more informed decision.
Whether you are taking your first loan after starting your career or planning for an important financial requirement, make sure you understand the commitment before borrowing.
Final Thoughts
Your first salary gives you financial freedom, but your first loan comes with financial responsibility. Before borrowing, understand your EMI, compare the total cost, check your CIBIL profile and make sure the repayment fits comfortably within your monthly budget.
Don’t borrow simply because you are eligible. Borrow when you understand why you need the money, how you will repay it and what the loan will cost you.
A strong financial journey starts with small, responsible decisions.
FAQs
Q1. Is it okay for a Gen Z professional to take their first personal loan?
A personal loan can be considered when there is a genuine financial requirement and the borrower has sufficient repayment capacity. The decision should be based on affordability rather than simply being eligible for a loan.
Q2. Does taking a personal loan affect my CIBIL Score?
A loan becomes part of your credit history. Your repayment behaviour, credit utilisation and lender enquiries are among the factors that can affect your CIBIL Score.
Q3. What should I check before taking my first loan?
Check the interest rate, EMI, repayment tenure, total repayment amount, applicable fees, late-payment charges, prepayment conditions and the lender’s terms and documentation.
Q4. Can I check my CIBIL Score before applying for a loan?
Yes. CIBIL provides access to your Score and Report, including a free Score and Report once per calendar year.
Q5. Should I take the maximum loan amount I am eligible for?
Not necessarily. Your eligibility and your comfortable repayment capacity are two different things. Consider your income, existing commitments, essential expenses and savings before deciding how much to borrow.